
Mortgage Rates at 6.7%? The Simple Trick to Buy Your Dream Home Right Now
Chattanooga Robert Wills December 22, 2025
Chattanooga Robert Wills December 22, 2025
If you've been watching mortgage rates climb and wondering if homeownership is still within reach, you're not alone. Many potential buyers in the Tennessee Valley have put their home search on hold, thinking that 6.7% rates make buying impossible. Here's the reality: you don't need to wait for rates to drop to secure your dream home.
The key isn't waiting for perfect conditions: it's understanding how to work with today's market effectively.
Current mortgage rates are more favorable than many buyers realize. As of December 2025, 30-year fixed mortgage rates are averaging around 6.04%, which represents an improvement from the 6.7% average we saw throughout most of the year.
While these rates are significantly higher than the historic lows of 2021, they remain within reasonable ranges for home financing. The difference between a 6.7% rate and today's 6.04% rate translates to meaningful monthly savings: approximately $60 less per month on principal and interest payments for a typical home purchase.
Over the life of a 30-year loan, that seemingly small difference saves buyers nearly $22,000 in total interest payments. This demonstrates why timing your purchase when rates are at the lower end of the current range can provide substantial long-term benefits.
The most effective approach to buying in today's market isn't waiting for dramatic rate changes: it's leveraging the tools and opportunities that exist right now. The strategy involves three key components: understanding rate buydowns, shopping multiple lenders, and choosing the right loan product.
Many buyers focus exclusively on the advertised rates they see online, missing opportunities to secure better terms through negotiation and proper loan selection. The real advantage comes from approaching your home purchase as a comprehensive financial strategy rather than simply accepting the first rate quote you receive.
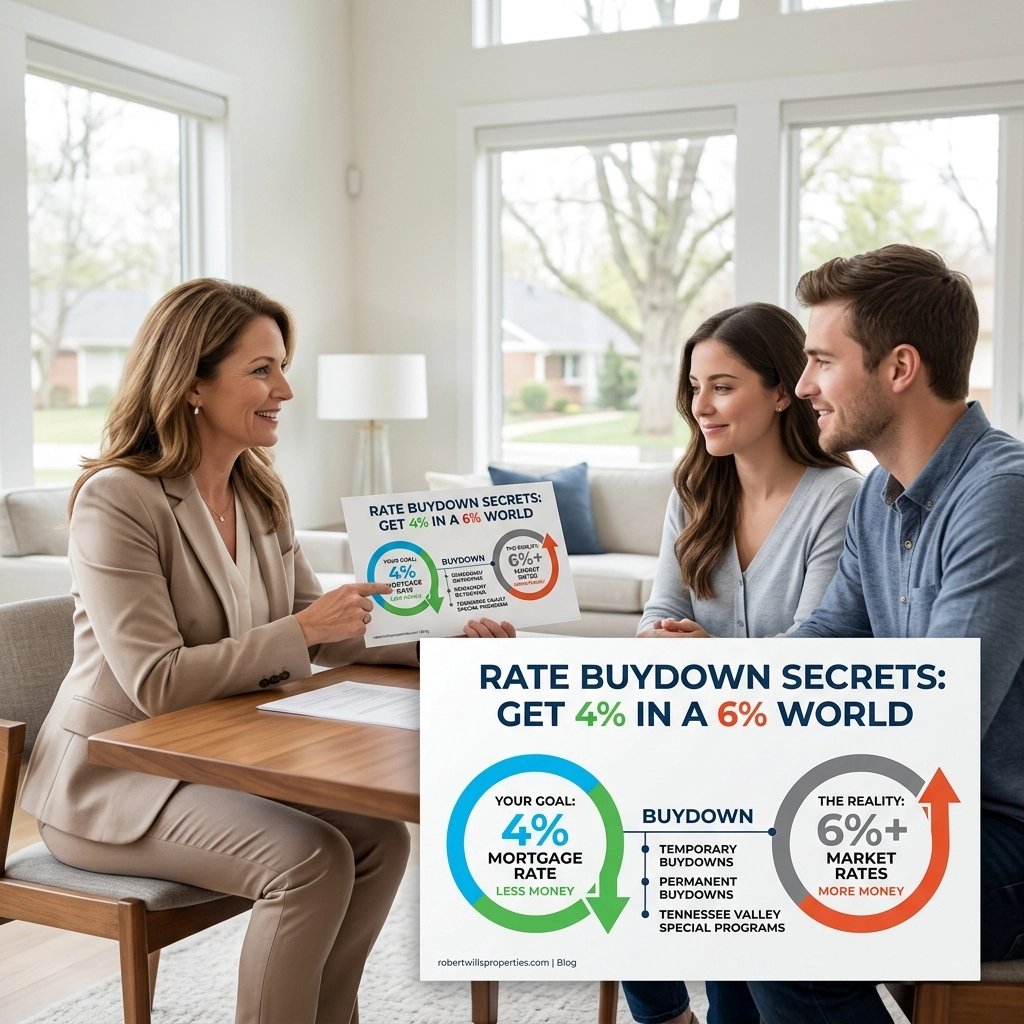
Rate buydowns have become increasingly common as builders and sellers seek to attract buyers in a challenging market. This strategy allows you to temporarily or permanently reduce your mortgage rate through upfront payments or seller concessions.
With newly constructed homes, builders often offer rate buydown incentives as part of their sales packages. These arrangements can reduce your rate by 1-2 percentage points for the first few years of your loan, significantly lowering your monthly payments during the early homeownership period.
For example, a builder might offer a 2-1 buydown, where your rate starts 2% below the market rate in year one, then 1% below in year two, before adjusting to the full market rate in year three. This structure provides immediate payment relief while you establish your homeownership routine.
Permanent buydowns, while requiring higher upfront costs, can provide rate reductions for the entire loan term. In competitive markets, sellers may contribute toward these costs as part of negotiations, effectively subsidizing your long-term financing.
Rate variations between lenders can be substantial, often ranging from 0.25% to 0.75% for similar loan products. This difference stems from varying business models, risk assessments, and current loan volume needs among different financial institutions.
Government-backed loans typically offer the most competitive rates. VA loans are currently averaging around 5.57%, while USDA and FHA loans often provide rates below conventional mortgage offerings. For qualified borrowers, these programs can reduce monthly payments by $100-200 compared to conventional financing.
Credit unions frequently offer competitive rates to their members, while online lenders may provide streamlined processes with favorable terms. Traditional banks often have more flexibility in negotiating rates for customers with existing relationships.
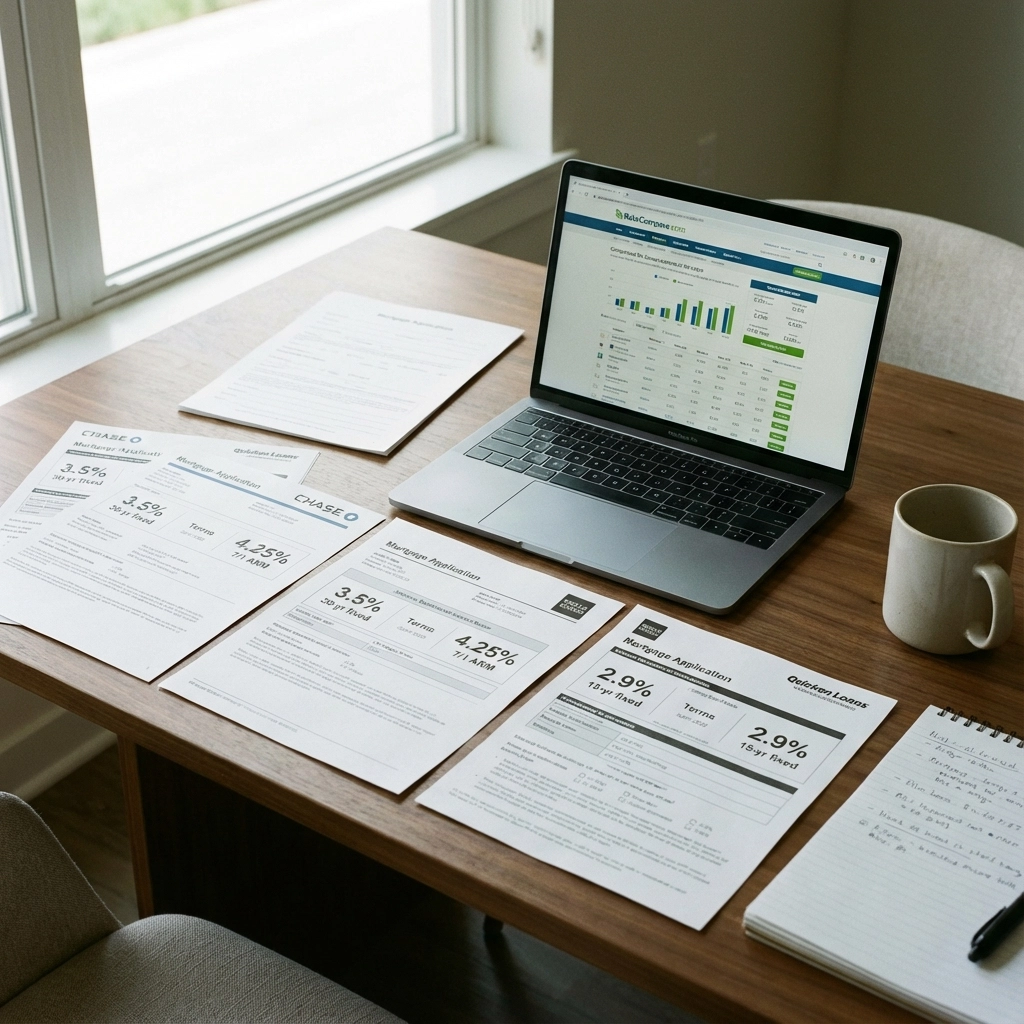
The key is obtaining quotes from at least three different types of lenders: a local bank, a credit union, and an online mortgage company. This comparison process typically takes 2-3 days but can result in thousands of dollars in savings over the loan term.
Your loan type significantly impacts both your initial rate and long-term costs. Conventional loans offer flexibility but may carry higher rates for buyers with smaller down payments. Government-backed options provide rate advantages but include specific eligibility requirements.
FHA loans accommodate buyers with credit scores as low as 580 and down payments of just 3.5%. While these loans require mortgage insurance, the lower rate and minimal down payment requirements make homeownership accessible sooner.
VA loans offer the most competitive rates available, with no down payment requirement and no mortgage insurance for qualifying veterans and service members. These loans often provide rates 0.5% below conventional options.
USDA loans serve buyers in eligible rural and suburban areas, offering 100% financing with competitive rates. Many areas in the Tennessee Valley qualify for USDA financing, making this an excellent option for buyers seeking homes outside urban centers.
The Tennessee Valley market presents unique opportunities for buyers willing to act strategically. Home inventory has increased compared to the previous year, giving buyers more options and negotiating power.
Many sellers are motivated to close before year-end, creating opportunities for buyers to secure favorable terms including seller-paid closing costs or rate buydown contributions. Properties that have been on the market for 60+ days often present the best negotiation opportunities.
New construction communities throughout North Georgia and Tennessee are offering attractive incentive packages, including rate buydowns, upgraded features, and closing cost assistance. These incentives can effectively reduce your overall homebuying costs by $10,000-15,000.
Understanding the financial impact of your timing and strategy helps clarify your options. A $300,000 home purchased with a 6.04% rate results in a monthly principal and interest payment of approximately $1,809. The same loan at 6.7% would cost $1,950 monthly: a difference of $141 per month.
Over five years, the lower rate saves $8,460 in total payments. These savings can fund home improvements, emergency reserves, or additional principal payments that further reduce your long-term costs.
The current market conditions favor buyers who understand these dynamics and act accordingly. While rates may continue fluctuating, the tools and strategies available today provide clear paths to homeownership success.
The most successful buyers in the current market share common characteristics: they secure pre-approval from multiple lenders, understand their loan options, and remain flexible about timing and property selection.
Begin by researching your loan eligibility for government-backed programs. Even if you assume you don't qualify, many buyers discover they meet requirements for VA, USDA, or FHA financing that offers significant rate advantages.
Work with a knowledgeable real estate professional who understands current market conditions and can identify properties where sellers are motivated to offer concessions. Properties with motivated sellers provide the best opportunities for securing rate buydowns or closing cost assistance.
Consider homes that have been on the market for extended periods, new construction with builder incentives, or properties in emerging neighborhoods where developers are offering attractive packages to drive sales.
The "simple trick" to buying your dream home isn't actually a trick at all: it's understanding how to use available tools effectively and timing your purchase when conditions align in your favor. Today's market provides those conditions for informed buyers ready to take action.
If you're ready to explore your options in the Tennessee Valley market, contact our team to discuss strategies tailored to your specific situation and goals.
Chattanooga
From riverfront concerts to mountain festivals, here is how to make the most of your 2026 summer in Chattanooga and North Georgia.
Chattanooga
Compare the true costs of renting versus buying in the Tennessee Valley and see if homeownership is closer than you think.
Chattanooga
Exploring the benefits of modern efficiency versus established charm in the 2026 Tennessee Valley market.
Chattanooga
Stop stressing over the headlines and learn how to secure a monthly payment that actually fits your budget.
Chattanooga
Why waiting for the "perfect" rate might be your most expensive mistake in the Tennessee Valley.
KellerhalsTeam
A simple, no-stress roadmap for Tennessee Valley and North Georgia buyers to secure their dream home before the summer heat hits.
Chattanooga
Discover the "City with Spirit" – the Tennessee Valley's best-kept secret for families, investors, and anyone tired of the "big city" price tag.
Chattanooga
Why waiting for the "perfect" number might actually cost you more in home price and competition than you’ll save in interest.
Chattanooga
Moving past the "bubble" talk and understanding the steady, sustainable growth of the 2026 real estate landscape in the Tennessee Valley and North Georgia.
Work with a dedicated real estate professional with deep roots in Chattanooga, who combines local expertise, a passion for client satisfaction, and cutting-edge technology to make your home-buying experience seamless and stress-free.